Savings & Cooperative Finance
SACCOs vs. Banks: Which Saves You More Over Five Years?
A data comparison of deposit rates, loan costs, and net returns to help you decide where your long-term savings belong.
The question Kenyan savers keep asking — with a real answer
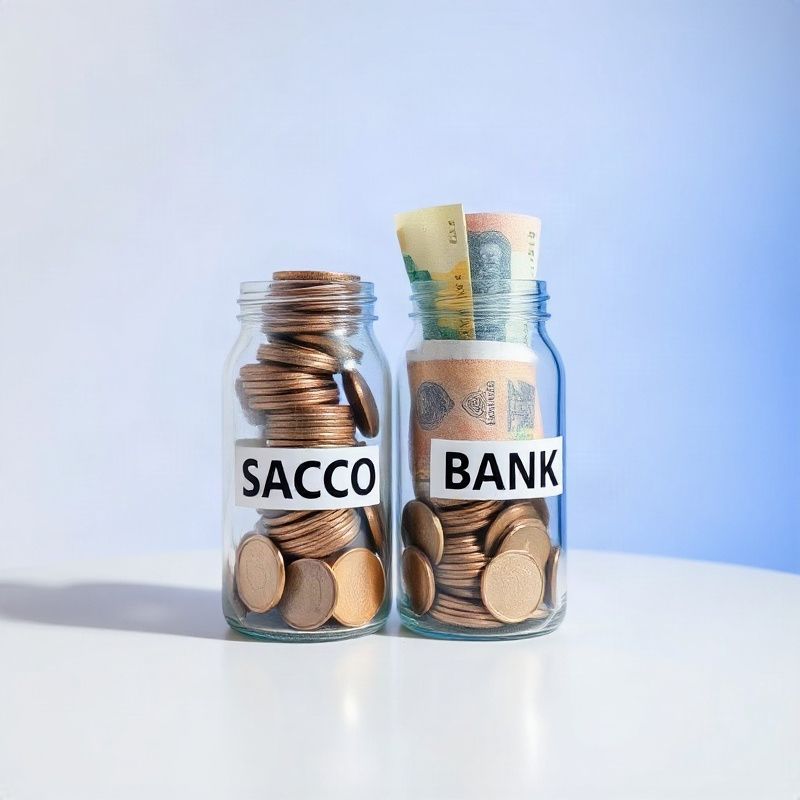
“Should I save at my SACCO or my bank?” is one of the most common questions in Kenyan personal finance, and it rarely gets a direct answer. Financial educators tend to say “it depends,” which is technically true but practically useless. This article gives you a direct answer — with the data behind it — for four distinct saver profiles. The comparison covers four Kenyan deposit-taking SACCOs and three commercial banks, using their published 2023 product terms. We examine five-year savings scenarios at three contribution levels: KSh 5,000, KSh 15,000, and KSh 30,000 per month. For each scenario, we calculate total deposits, interest or dividend income, net return after any charges, and the effective annual yield. We also factor in the SACCO share dividend — the component that most savers overlook when comparing returns — and the cost of accessing a salary advance or emergency loan at each institution. The results are more definitive than you might expect. For the majority of salaried Kenyan employees contributing consistently over five years, a well-managed deposit-taking SACCO returns between 1.8 and 2.6 percentage points more per year than a standard commercial bank savings account. The gap is largest for contributors above KSh 15,000 per month, where the SACCO share dividend has the most impact. Banks retain a meaningful advantage in liquidity — accessing funds quickly and without penalty is easier — and in the range of payment and digital services offered. The right choice depends on how much weight you place on returns versus flexibility.
Key findings and how to apply them to your situation
Across the four SACCOs in our sample, average five-year effective yields ranged from 9.4 to 11.7 percent per annum, incorporating both the deposit interest rate and the average share dividend declared over the period. The three commercial banks in the sample returned between 6.8 and 8.2 percent on fixed-deposit accounts and between 3.1 and 4.5 percent on standard savings accounts. Ordinary savings accounts at banks — the type most Kenyans hold their salary in — perform the worst in this comparison and should not be used as a long-term savings vehicle. If you are a salaried employee with a stable income and a savings horizon of at least three years, the data supports prioritizing your SACCO contribution over a bank savings account. The practical caveat is SACCO selection: not all SACCOs are equally well managed. Before committing, verify that the SACCO is licensed by the SACCO Societies Regulatory Authority (SASRA), check its most recent annual report for the dividend declared per share over the past three years, and review its non-performing loan ratio — a figure above 10 percent is a warning sign. If your employer SACCO is SASRA-regulated and has declared dividends consistently above 9 percent for three or more years, it is almost certainly a better long-term savings vehicle than a standard bank account.
Found this comparison useful?
The Sparksforge newsletter delivers one analysis like this every Friday — free, directly to your inbox.